Surviving Spouse Social Security Benefits: Age 60 vs. Full Retirement Age
Advertisements
Latest developments on Surviving Spouse Social Security Benefits: How Claiming at Age 60 vs. Full Retirement Age Impacts 28.5% of Value, with key facts, verified sources and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Estados Unidos) (en-US).
Surviving Spouse Social Security Benefits: How Claiming at Age 60 vs. Full Retirement Age Impacts 28.5% of Value is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters and what to watch next, in a straightforward news format.
Understanding Surviving Spouse Social Security Benefits
For many Americans, the death of a spouse brings not only emotional distress but also significant financial uncertainty. Navigating the complexities of Social Security survivor benefits is a critical step in securing one's financial future during such a challenging time.
The decision of when to claim these benefits can have profound, long-lasting implications on the total amount received over a lifetime. This choice, specifically between claiming at age 60 or waiting until Full Retirement Age (FRA), is often misunderstood.
Understanding the rules and potential financial impact is essential for surviving spouses to make informed decisions that maximize their financial well-being. The difference in value can be substantial, as much as 28.5%.
The Critical Choice: Age 60 vs. Full Retirement Age
The Social Security Administration (SSA) allows surviving spouses to begin receiving benefits as early as age 60, or age 50 if disabled. However, opting for early claiming comes with a significant reduction in monthly payments.
Waiting until your Full Retirement Age (FRA), which varies depending on your birth year, ensures you receive 100% of the deceased spouse's primary insurance amount (PIA). This fundamental difference forms the core of the 28.5% impact.
This percentage represents the maximum reduction a surviving spouse can face by claiming at the earliest possible age (60) compared to waiting until their FRA. This is a crucial factor in long-term financial planning.
Early Claiming Penalties Explained
When a surviving spouse claims benefits at age 60, their monthly payment is permanently reduced. The reduction is approximately 28.5% for those whose FRA is 67, meaning they would receive only 71.5% of the deceased spouse's full benefit.
This reduction is applied because the SSA expects to pay benefits for a longer period. The actuarial adjustment aims to equalize the total lifetime benefits paid, but the monthly amount is significantly lower.
Understanding this permanent reduction is vital, as it directly affects a surviving spouse's disposable income for potentially decades. It is not merely a temporary decrease but a fixed adjustment for the remainder of their life.
Benefits of Waiting Until Full Retirement Age
Delaying the claim for surviving spouse benefits until your Full Retirement Age (FRA) ensures you receive 100% of the deceased spouse's primary insurance amount. This can be a substantial increase in monthly income compared to early claiming.
For individuals with a longer life expectancy, waiting until FRA often translates to a higher total lifetime benefit, despite receiving fewer payments initially. The higher monthly payout provides greater financial security in later years.
This strategy is particularly beneficial if the surviving spouse has other income sources to support themselves until FRA, allowing them to maximize their Social Security entitlement.
Calculating the 28.5% Impact on Surviving Spouse Benefits
The 28.5% figure represents the maximum reduction for claiming surviving spouse benefits at age 60, assuming the surviving spouse's Full Retirement Age is 67. For every month before FRA that benefits are claimed, a reduction is applied.
For example, if a deceased spouse's full benefit was $2,000, claiming at age 60 would reduce the monthly payment to approximately $1,430. This difference of $570 per month accumulates to a significant sum over many years.
It's important to use the SSA's specific reduction factors based on your birth year to get a precise calculation, as the exact percentage can vary slightly. However, the general principle of a substantial reduction for early claiming holds true.
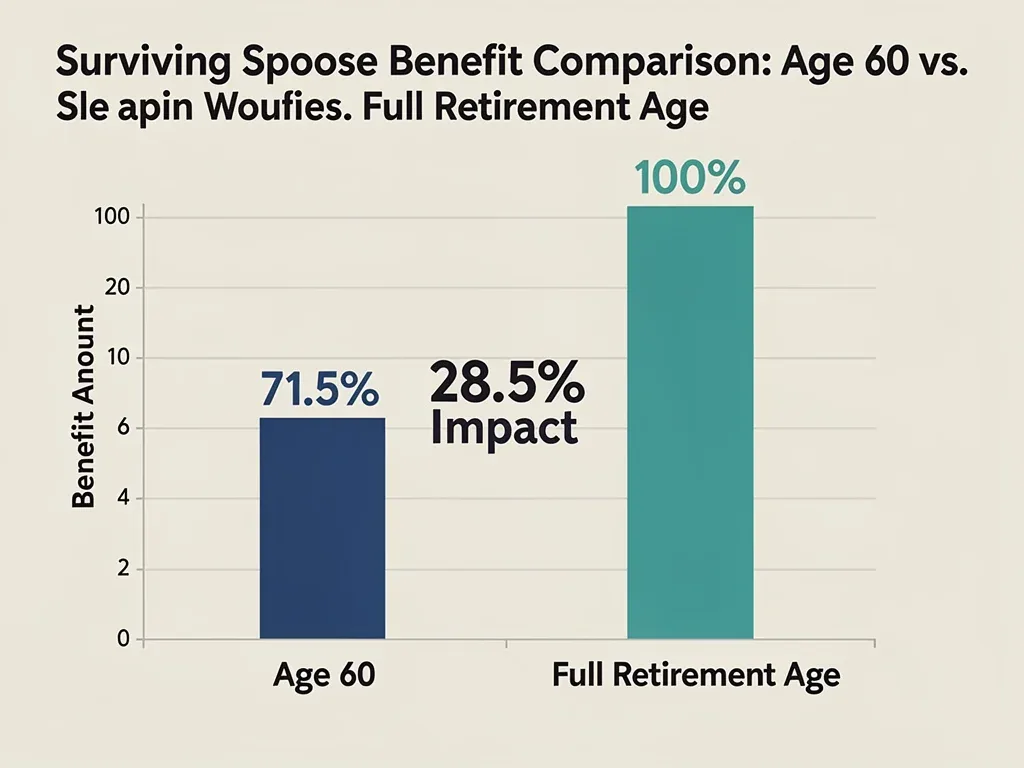
Factors Influencing the Claiming Decision
Several personal and financial factors play a crucial role in deciding when to claim surviving spouse benefits. There is no one-size-fits-all answer, and individual circumstances heavily dictate the optimal strategy.
A surviving spouse's current financial needs, health status, and the availability of other income sources are paramount considerations. These elements help determine if the immediate need for income outweighs the long-term benefit reduction.
Furthermore, the surviving spouse's own work history and potential eligibility for their own Social Security retirement benefits can significantly impact the decision-making process. Coordination of benefits is key.
Current Financial Needs and Health
Immediate financial hardship often compels surviving spouses to claim benefits at age 60. If there are insufficient savings, ongoing expenses, or a lack of other income, early claiming might be a necessary lifeline.
However, it is vital to weigh this immediate relief against the permanent reduction. A thorough assessment of current income, expenses, and available assets is crucial before making a decision.
Health status and life expectancy are also significant factors. A surviving spouse facing serious health issues might prioritize receiving benefits sooner, while someone in good health might consider waiting for higher payments.
Coordination with Personal Retirement Benefits
Surviving spouses may also be eligible for their own Social Security retirement benefits based on their work record. The SSA allows individuals to claim one benefit first and switch to the higher one later, if applicable.
For example, a surviving spouse might claim reduced survivor benefits at age 60 and then switch to their own, potentially higher, retirement benefit at age 70. This strategy can maximize total lifetime income.
Understanding the claiming options and how they interact is complex, often requiring careful planning and potentially professional financial advice to optimize the outcome for surviving spouse benefits.
Strategies for Maximizing Surviving Spouse Benefits
Strategic claiming can significantly increase the total value received from surviving spouse benefits. This often involves a careful analysis of individual circumstances and understanding the interplay between different benefit types.
One common strategy is to claim surviving spouse benefits early and allow one's own retirement benefit to grow. Conversely, waiting to claim survivor benefits while receiving one's own retirement benefits can also be advantageous.
The optimal strategy depends heavily on the age of the surviving spouse, their earnings history, and the deceased spouse's benefit amount. Expert guidance is often invaluable in navigating these choices.
"File and Suspend" for Survivors (Limited Cases)
While the "file and suspend" strategy for retirement benefits was largely eliminated, certain aspects or similar principles can still apply in limited scenarios for surviving spouses, particularly concerning coordination with their own retirement benefits.
A surviving spouse might claim survivor benefits at their FRA and then suspend their own retirement benefits until age 70 to earn delayed retirement credits. This allows their own benefit to grow significantly.
This complex strategy requires a deep understanding of Social Security rules and is best discussed with a financial advisor specializing in Social Security planning to ensure compliance and maximize benefits.
The Role of Financial Planning
Effective financial planning is paramount when making decisions about surviving spouse benefits. A comprehensive plan considers all income sources, expenses, assets, and future financial goals.
A financial advisor can help surviving spouses analyze their specific situation, project future benefit amounts, and model different claiming scenarios. This personalized guidance is crucial for informed decision-making.
Given the permanent nature of the claiming decision and the potential 28.5% impact on value, investing in professional advice can yield substantial returns in maximized lifetime benefits.
Impact on Long-Term Financial Security
The decision regarding when to claim surviving spouse benefits has a direct and significant impact on a surviving individual's long-term financial security. A difference of 28.5% in monthly income can translate to hundreds of thousands of dollars over a lifetime.
This financial disparity can affect a surviving spouse's ability to cover essential living expenses, maintain their lifestyle, and even fund unexpected healthcare costs in retirement. The compounding effect of a lower monthly benefit is substantial.
Therefore, understanding these long-term implications is not just about maximizing a number, but about ensuring dignity and financial independence throughout the remaining years of life for the surviving spouse.
Recent Updates and Future Considerations
Social Security rules and regulations are subject to change, albeit typically slowly. Surviving spouses should remain aware of any legislative developments that could impact their benefits.
While the core principles of claiming at age 60 versus Full Retirement Age have remained consistent, broader discussions about Social Security's solvency could introduce future adjustments. Staying informed is crucial.
The Social Security Administration regularly updates its resources and tools, and surviving spouses should utilize these to stay current on their specific benefit entitlements and any new guidance.
| Key Point | Brief Description |
|---|---|
| Claiming Age Impact | Claiming surviving spouse benefits at age 60 can reduce monthly payments by up to 28.5% compared to Full Retirement Age. |
| Full Retirement Age (FRA) | Waiting until FRA ensures 100% of the deceased spouse's primary insurance amount, maximizing monthly benefits. |
| Financial Planning | Strategic planning, often with professional advice, is crucial to coordinate survivor benefits with personal retirement benefits. |
| Long-Term Security | The claiming decision significantly impacts a surviving spouse's financial well-being for decades, affecting overall lifestyle. |
Frequently Asked Questions About Surviving Spouse Social Security Benefits
What are Surviving Spouse Social Security Benefits?▼Surviving Spouse Social Security Benefits are payments made to a widow, widower, or in some cases, a divorced spouse, based on the earnings record of their deceased spouse. These benefits aim to provide financial support after the loss of a partner, helping to maintain their standard of living.
How does claiming at age 60 impact the benefit amount?▼Claiming surviving spouse benefits at age 60 results in a permanent reduction of up to 28.5% compared to receiving benefits at Full Retirement Age (FRA). This reduction is applied because the benefits are paid out over a longer period, resulting in lower monthly payments.
Is it always better to wait until Full Retirement Age (FRA)?▼Not always. While waiting until FRA maximizes monthly payments, claiming early might be necessary due to immediate financial needs or health considerations. The optimal choice depends on individual circumstances, including other income sources and life expectancy. Professional advice is recommended.
Can I switch from survivor benefits to my own retirement benefits later?▼Yes, often. A surviving spouse can claim survivor benefits first, and then switch to their own retirement benefits later if their own benefit amount becomes higher. This strategy can be complex but allows for maximization of total lifetime Social Security income. It requires careful planning.
Where can I get personalized advice on my surviving spouse benefits?▼For personalized guidance, it is highly recommended to consult with a qualified financial advisor specializing in Social Security planning. The Social Security Administration also provides resources and calculators on its official website to help you understand your specific benefit options and estimates.
What this means
The decision surrounding Surviving Spouse Social Security Benefits: How Claiming at Age 60 vs. Full Retirement Age Impacts 28.5% of Value represents a pivotal financial moment for many. Understanding this critical 28.5% difference is not merely an academic exercise; it directly affects daily living and long-term financial stability. Surviving spouses must carefully evaluate their financial situation, health, and other potential income streams to make the most informed decision. Consulting with financial experts and utilizing official SSA resources remains paramount to navigating these complex choices effectively.