ACA Subsidies 2026: 10% Premium Tax Credit Increase Impact
Advertisements
Latest developments on Understanding the 2026 Affordable Care Act (ACA) Subsidies: What a 10% Increase in Premium Tax Credits Means for You, with key facts, verified sources and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Estados Unidos) (en-US).
Understanding the 2026 Affordable Care Act (ACA) Subsidies: What a 10% Increase in Premium Tax Credits Means for You is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters and what to watch next, in a straightforward news format.
The landscape of healthcare affordability in the United States is poised for a significant shift in 2026, driven by an anticipated 10% increase in premium tax credits under the Affordable Care Act (ACA). This adjustment is designed to make health insurance more accessible and affordable for millions of Americans, particularly those in lower and middle-income brackets.
This substantial boost in financial assistance will directly reduce the burden of monthly premium payments, allowing more individuals and families to secure comprehensive health coverage. The implications extend beyond immediate cost savings, potentially leading to improved health outcomes and greater financial security for beneficiaries.
As the 2026 implementation approaches, understanding the nuances of these enhanced subsidies becomes paramount for consumers, policymakers, and healthcare providers alike. This article delves into the specifics of this change, its potential impact, and what individuals need to know to navigate the evolving ACA marketplace.
The Mechanics of ACA Subsidies and Premium Tax Credits
ACA subsidies, officially known as premium tax credits, are financial assistance provided by the federal government to help eligible individuals and families afford health insurance purchased through the Health Insurance Marketplace. These credits are instrumental in lowering monthly premium costs, making coverage attainable for those who might otherwise find it too expensive.
Eligibility for these subsidies is primarily determined by household income relative to the federal poverty level (FPL), as well as household size. The current system caps the percentage of income individuals must pay for their health insurance, with the premium tax credits covering the difference between this cap and the actual premium cost.
The upcoming 10% increase signifies a reduction in the percentage of income individuals are expected to contribute towards their premiums, effectively boosting the amount of the subsidy received. This adjustment aims to further alleviate financial strain, particularly for those facing rising healthcare costs.
How Premium Tax Credits are Calculated
Premium tax credits are calculated on a sliding scale, meaning individuals with lower incomes receive larger subsidies. The calculation considers your household income, household size, and the cost of the second-lowest-cost Silver plan available in your area.
The 10% increase will adjust the income percentages used in this calculation, making a larger portion of the premium eligible for federal assistance. This means a lower out-of-pocket maximum for premiums for many enrollees, potentially freeing up household budgets for other essential needs.
This enhancement is a direct response to ongoing concerns about healthcare affordability and access, reflecting a commitment to strengthen the ACA’s foundational goal of ensuring more Americans have health coverage.
- Household income relative to the Federal Poverty Level (FPL) is a primary determinant.
- Household size plays a crucial role in establishing eligibility and subsidy amounts.
- The cost of the benchmark Silver plan in your region is used to calculate the credit.
The system is designed to prevent individuals from paying an excessive percentage of their income on health insurance premiums. The 2026 adjustment will make this protection even more robust, widening the net of affordability.
Impact of the 10% Increase on Enrollees
The 10% increase in premium tax credits for 2026 is projected to have a profound impact on millions of Americans, particularly those who currently rely on ACA subsidies or are on the cusp of eligibility. This enhancement will translate into tangible savings on monthly premiums, making health insurance more affordable than ever for many.
For existing enrollees, the most immediate benefit will be a reduction in their out-of-pocket premium costs, potentially allowing them to choose more comprehensive plans or save money for other healthcare expenses. For those who previously found ACA plans too expensive, this increase could make coverage a viable option.
The enhanced affordability is also expected to encourage greater enrollment in the Health Insurance Marketplace, reducing the number of uninsured individuals across the country. This expansion of coverage could lead to a healthier population overall, with fewer people delaying necessary medical care due to cost concerns.
Who Benefits Most from Enhanced ACA Subsidies 2026?
Individuals and families with incomes between 100% and 400% of the federal poverty level are the primary beneficiaries of ACA premium tax credits. The 2026 increase will significantly reduce the net cost of premiums for this group, making health insurance much more accessible.
Notably, those at the lower end of this income spectrum will likely see the most substantial percentage decrease in their premium contributions. However, even those with higher incomes within the eligible range will experience noticeable savings, broadening the appeal of marketplace plans.
This targeted support aims to close gaps in coverage and ensure that financial barriers do not prevent individuals from accessing essential health benefits. The increase is a strategic move to reinforce the ACA’s core objective of universal access.
- Lower-income households will experience the most significant proportional savings.
- Middle-income families will also see reduced premium burdens, enhancing overall affordability.
- Individuals near the 400% FPL threshold may now qualify for substantial assistance.
The expansion of eligibility and the increased financial relief underscore the government’s commitment to bolstering the ACA’s effectiveness. This change is not merely incremental but represents a significant step towards more equitable healthcare access.
Navigating the 2026 Enrollment Period
As 2026 approaches, understanding how to navigate the Health Insurance Marketplace will be crucial for maximizing the benefits of the increased ACA subsidies. The open enrollment period is the primary time when individuals can select or change their health plans and apply for financial assistance.
It is essential for both new and returning enrollees to accurately report their household income and family size during the application process. Any discrepancies can affect subsidy calculations and potentially lead to repayment obligations at tax time.
The Marketplace offers various tools and resources, including navigators and assisters, to help individuals understand their options and complete the enrollment process. Utilizing these resources can ensure that you receive the maximum financial assistance you are eligible for under the enhanced ACA Subsidies 2026.
Key Steps for Enrollment and Understanding Your Benefits
Begin by visiting HealthCare.gov or your state’s marketplace website to explore available plans and estimate your potential subsidies. The platform provides tools to compare plans based on cost, coverage, and provider networks.
Gather necessary documentation, such as income statements and household information, to ensure a smooth application process. Being prepared will help avoid delays and ensure timely access to coverage.
Consider consulting with a certified navigator or insurance broker who can offer personalized guidance and clarify complex aspects of the ACA and its subsidies. These experts can be invaluable resources in making informed decisions about your healthcare.
- Accurately report income and household changes to prevent subsidy adjustments.
- Compare different plan metallic levels (Bronze, Silver, Gold, Platinum) to find the best fit.
- Be aware of the open enrollment dates to ensure continuous coverage.
Proactive engagement with the enrollment process will ensure that you are well-positioned to take full advantage of the increased premium tax credits. This foresight can lead to significant annual savings and better health outcomes.
Potential Broader Economic and Health Impacts
The 10% increase in ACA premium tax credits for 2026 is not just a policy adjustment; it is a measure with far-reaching potential economic and public health implications. By making health insurance more affordable, the initiative aims to reduce the financial precarity many Americans face when confronting medical emergencies.
Economically, reduced healthcare costs for individuals can free up disposable income, potentially stimulating local economies. Businesses might also benefit from a healthier workforce, leading to increased productivity and fewer missed workdays due to illness.
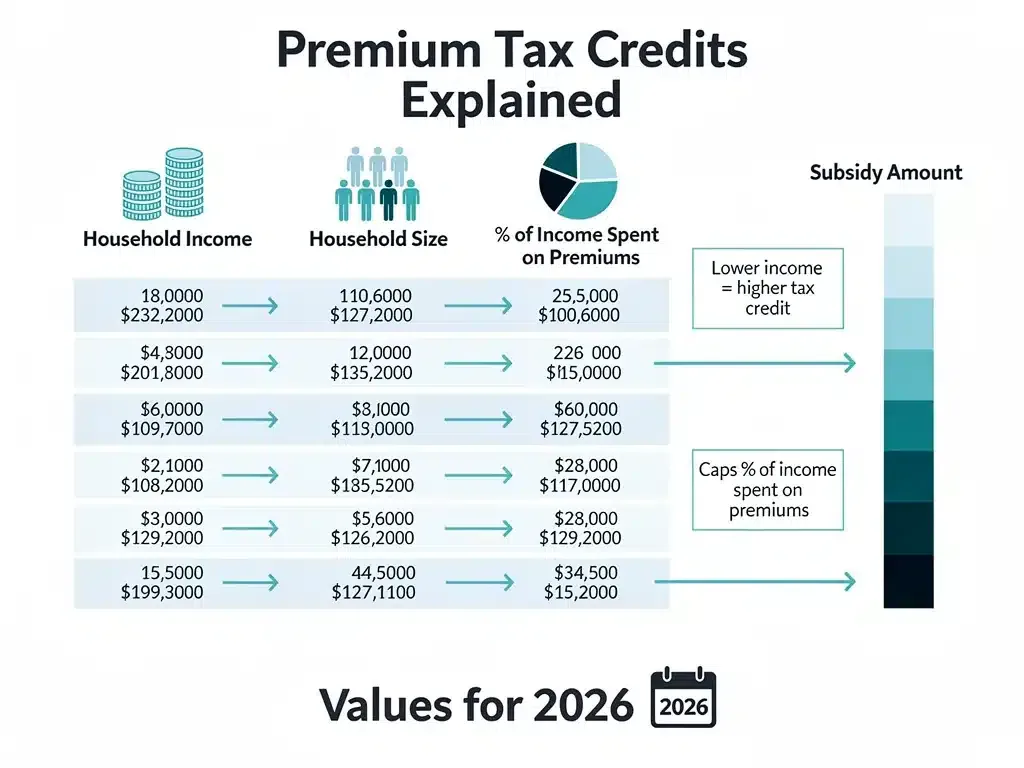
From a public health perspective, broader insurance coverage means more people can access preventive care, early diagnosis, and ongoing treatment for chronic conditions. This shift can lead to improved population health outcomes, reducing the incidence of severe illness and the overall burden on emergency services.
Long-Term Benefits of Enhanced Affordability
When more people have affordable health insurance, there’s a collective benefit to public health. Regular access to care helps manage chronic diseases, preventing them from escalating into more serious and costly conditions.
The reduction in medical debt, a significant cause of personal bankruptcy in the U.S., is another critical long-term benefit. By mitigating out-of-pocket costs, the enhanced subsidies can protect families from financial ruin due to unexpected health issues.
This investment in healthcare affordability can also lead to a more stable and resilient society, where individuals feel more secure about their health and financial future. The ripple effects of ACA Subsidies 2026 are expected to be substantial.
- Reduced medical debt contributes to greater financial stability for families.
- Increased access to preventive care can lower overall healthcare expenditures in the long run.
- A healthier population can lead to a more productive and engaged workforce.
The enhanced subsidies represent a strategic investment in the well-being and economic stability of the nation. The foresight behind these changes points to a future where healthcare is a right, not a privilege.
Addressing Common Concerns and Misconceptions
Despite the clear benefits, changes to healthcare policy often come with questions and potential misconceptions. It’s crucial to address these to ensure that the public has accurate information regarding the 2026 ACA subsidies and the 10% increase in premium tax credits.
One common concern revolves around the sustainability of such increases and their impact on federal spending. While the boost in subsidies does represent an increased federal investment, proponents argue that the long-term benefits of a healthier population and reduced uncompensated care outweigh these costs.
Another area of confusion might be how these changes interact with other healthcare programs, such as Medicaid or Medicare. It is important to clarify that ACA subsidies primarily apply to plans purchased through the marketplace and are distinct from other government health programs, though eligibility for one can sometimes affect eligibility for another.
Ensuring Accurate Information and Understanding
The complexity of healthcare policy can be daunting, leading to misunderstandings about how the ACA Subsidies 2026 will work. Official government websites and trusted non-profit organizations are the best sources for accurate and up-to-date information.
Be wary of misinformation, especially concerning eligibility criteria or the extent of the benefits. Always cross-reference information with official sources to ensure you are receiving correct guidance.
Educational campaigns are expected to roll out closer to 2026 to help clarify these points. These initiatives will be vital in empowering consumers to make informed decisions about their healthcare coverage.
- Verify information from official government sources like HealthCare.gov.
- Consult with certified navigators or insurance agents for personalized advice.
- Stay informed about any legislative updates that might impact the subsidies.
Proactive engagement with reliable information will help individuals fully grasp the advantages offered by the increased premium tax credits. This ensures that the intended benefits reach those who need them most.
The Legislative Context and Future Outlook
The decision to implement a 10% increase in premium tax credits for 2026 is rooted in ongoing legislative efforts to strengthen the Affordable Care Act and address healthcare affordability challenges. This move reflects a broader policy agenda aimed at expanding access to quality healthcare for all Americans.
While the increase is set for 2026, the legislative discussions and policy debates leading up to this decision have been continuous, underscoring the dynamic nature of healthcare policy. Future adjustments or extensions of these enhanced subsidies will depend on ongoing political will and economic conditions.
Stakeholders, including advocacy groups, healthcare providers, and insurance companies, will continue to monitor the implementation and impact of these changes. Their feedback and data will be crucial in shaping future policy decisions related to ACA subsidies.
What Could Influence Future ACA Subsidy Decisions?
Economic indicators, such as inflation and employment rates, will play a significant role in future policy discussions regarding healthcare affordability. The government’s ability to fund these subsidies is directly tied to the national economic landscape.
Political shifts and election outcomes could also influence the longevity and scope of enhanced ACA subsidies. Different administrations may prioritize varying approaches to healthcare reform.
Public health needs and emerging health crises may also drive future legislative action. The lessons learned from previous health challenges often inform policy adjustments aimed at strengthening the healthcare system.
- Economic stability and federal budget considerations are key factors.
- Political climate and upcoming elections can reshape healthcare priorities.
- Public health demands and evolving healthcare challenges will influence future policy.
The ACA Subsidies 2026 increase is a significant milestone, but the conversation around healthcare affordability and access is ongoing. Remaining informed about legislative developments is essential for understanding the evolving landscape.
Comparing 2025 vs. 2026 ACA Subsidies
To fully appreciate the impact of the 10% increase, it’s helpful to compare the subsidy structure in 2025 with what is anticipated for 2026. This comparison highlights the tangible benefits that enrollees can expect from the enhanced premium tax credits.
In 2025, individuals and families will continue to receive premium tax credits based on the existing formula, which caps the percentage of income spent on premiums at a certain level. While this provides significant relief, the 2026 adjustment will make an even greater difference.
The 10% increase means that for the same income level and plan, an enrollee in 2026 will pay a lower percentage of their income towards premiums compared to 2025. This effectively translates to more money in their pockets each month.
Quantifying the Difference in Premium Payments
For an individual earning 200% of the FPL, the 2026 increase could mean several hundred dollars in annual savings on premiums. This cumulative effect can significantly impact household budgets over time.
Families, especially those with multiple members, will also see substantial reductions in their overall healthcare costs. The enhanced subsidies aim to ensure that healthcare remains within reach for a broader segment of the population.
Understanding this year-over-year difference is crucial for financial planning and for making informed decisions during the open enrollment periods. The ACA Subsidies 2026 represent a clear improvement in affordability.
- The percentage of income spent on premiums will decrease for eligible enrollees in 2026.
- Actual dollar savings will vary based on income, household size, and plan choice.
- This change provides a clearer financial advantage for choosing marketplace plans.
This direct comparison underscores the government’s commitment to making healthcare more affordable and accessible. The 2026 changes are designed to provide a more robust safety net for American families.
Eligibility and Enrollment for 2026 Subsidies
To benefit from the ACA Subsidies 2026, understanding the eligibility requirements and the enrollment process is critical. While the increase in premium tax credits will make coverage more affordable, the core eligibility criteria largely remain consistent.
Generally, you are eligible for premium tax credits if your household income is between 100% and 400% of the federal poverty level. However, some exceptions apply, particularly for those in states that have not expanded Medicaid.
During the open enrollment period for 2026 plans, individuals will need to apply through their state’s Health Insurance Marketplace or HealthCare.gov. Accurate reporting of income and household changes is paramount to ensure correct subsidy calculations.
Key Eligibility Criteria and Application Tips
Your household income is a primary factor. It includes most taxable income, such as wages, salaries, and net self-employment income, as well as certain untaxed foreign income and Social Security benefits.
You must not be eligible for other minimum essential coverage, such as Medicare, Medicaid, CHIP, or affordable employer-sponsored insurance. If your employer offers affordable coverage, you typically won’t qualify for ACA subsidies.
When applying, be prepared to provide documentation that verifies your income and household size. This could include tax returns, pay stubs, or other financial records. Accuracy will streamline your application and prevent future issues.
- Income between 100% and 400% FPL is the general guideline for eligibility.
- Non-eligibility for other forms of minimum essential coverage is a key requirement.
- Accurate documentation of income and household size is vital for correct subsidy determination.
Understanding these fundamental aspects of eligibility and preparing thoroughly for enrollment will ensure you can take full advantage of the enhanced ACA Subsidies 2026.
| Key Point | Brief Description |
|---|---|
| Subsidy Increase | Premium tax credits under ACA will increase by 10% in 2026. |
| Affordability Boost | Reduces monthly premium costs, making health insurance more accessible. |
| Eligibility | Primarily for incomes between 100% and 400% of the Federal Poverty Level. |
| Enrollment Impact | Expected to drive higher enrollment and improved public health outcomes. |
Frequently Asked Questions About ACA Subsidies 2026
What exactly does a 10% increase in premium tax credits mean for me?▼A 10% increase in premium tax credits means you will pay a smaller percentage of your income towards your health insurance premiums in 2026. This translates to a larger subsidy amount, reducing your monthly out-of-pocket costs for coverage purchased through the ACA Marketplace.
Who is eligible for these enhanced ACA Subsidies 2026?▼Eligibility primarily depends on your household income relative to the federal poverty level, typically between 100% and 400% FPL. Your household size and the cost of the benchmark Silver plan in your area also factor into the final subsidy amount you receive.
When will these increased subsidies take effect?▼The 10% increase in premium tax credits is scheduled to take effect for the 2026 plan year. This means that when you enroll in or re-enroll for coverage during the open enrollment period for 2026, the enhanced subsidy calculations will be applied.
Will the increased ACA Subsidies 2026 affect my existing health plan?▼If you are currently enrolled in an ACA Marketplace plan and remain eligible for subsidies, your premium tax credit will be recalculated for 2026 to reflect the 10% increase. This should result in lower monthly premiums for the same or similar plan, offering greater affordability.
Where can I find more information about these changes and enroll?▼You can find comprehensive and up-to-date information, and enroll, by visiting HealthCare.gov or your state’s official Health Insurance Marketplace website. These platforms offer tools to estimate subsidies and compare plans, and provide access to certified navigators for assistance.
Looking Ahead: The Future of ACA Affordability
The 10% increase in premium tax credits for 2026 marks a significant step towards bolstering the affordability of healthcare under the Affordable Care Act. This enhancement is expected to translate into tangible savings for millions of Americans, making health insurance more accessible and reducing the financial burden of medical care. The ongoing commitment to strengthening the ACA Subsidies 2026 framework underscores a broader vision for a healthier, more financially secure nation. As these changes take effect, continuous monitoring and public engagement will be vital to assess their full impact and inform future policy adjustments.